At a glance
- ₹854.9 crore consolidated H1 FY27 revenue, up 6.3%.
- ₹354.3 crore Q2 revenue, down 16.8%.
- 13.32% Q2 EBITDA margin, against 18.87% a year earlier.
- Approximately ₹2,700 crore international order book.
Executive summary
WPIL’s international operations helped lift consolidated revenue in the first half of FY2027, even as Indian revenue declined sharply. The latest quarter, however, shows why geographical diversification alone cannot settle the question of operating recovery. Revenue fell and margins narrowed in the three months ended September. The company’s 31 October presentation points to customer-deferred dispatches, domestic project completion and overseas execution as the milestones that will determine what happens next.
What changed
Consolidated first-half revenue reached ₹854.9 crore, up 6.3% from ₹804.6 crore. Profit after tax rose 19.5% to ₹92.6 crore, but EBITDA declined 5.4% to ₹122.5 crore. The EBITDA margin narrowed from 16.11% to 14.33%. These figures, converted from the presentation’s million-rupee financial tables, show that higher revenue and profit did not mean stronger operating margins.
The September quarter was weaker: consolidated revenue fell 16.8% year on year to ₹354.3 crore, while profit after tax declined 35.1% to ₹33.6 crore. The quarterly EBITDA margin was 13.32%, against 18.87% a year earlier. A half-year growth headline therefore needs to be read alongside the more recent quarter.
Two different operating stories
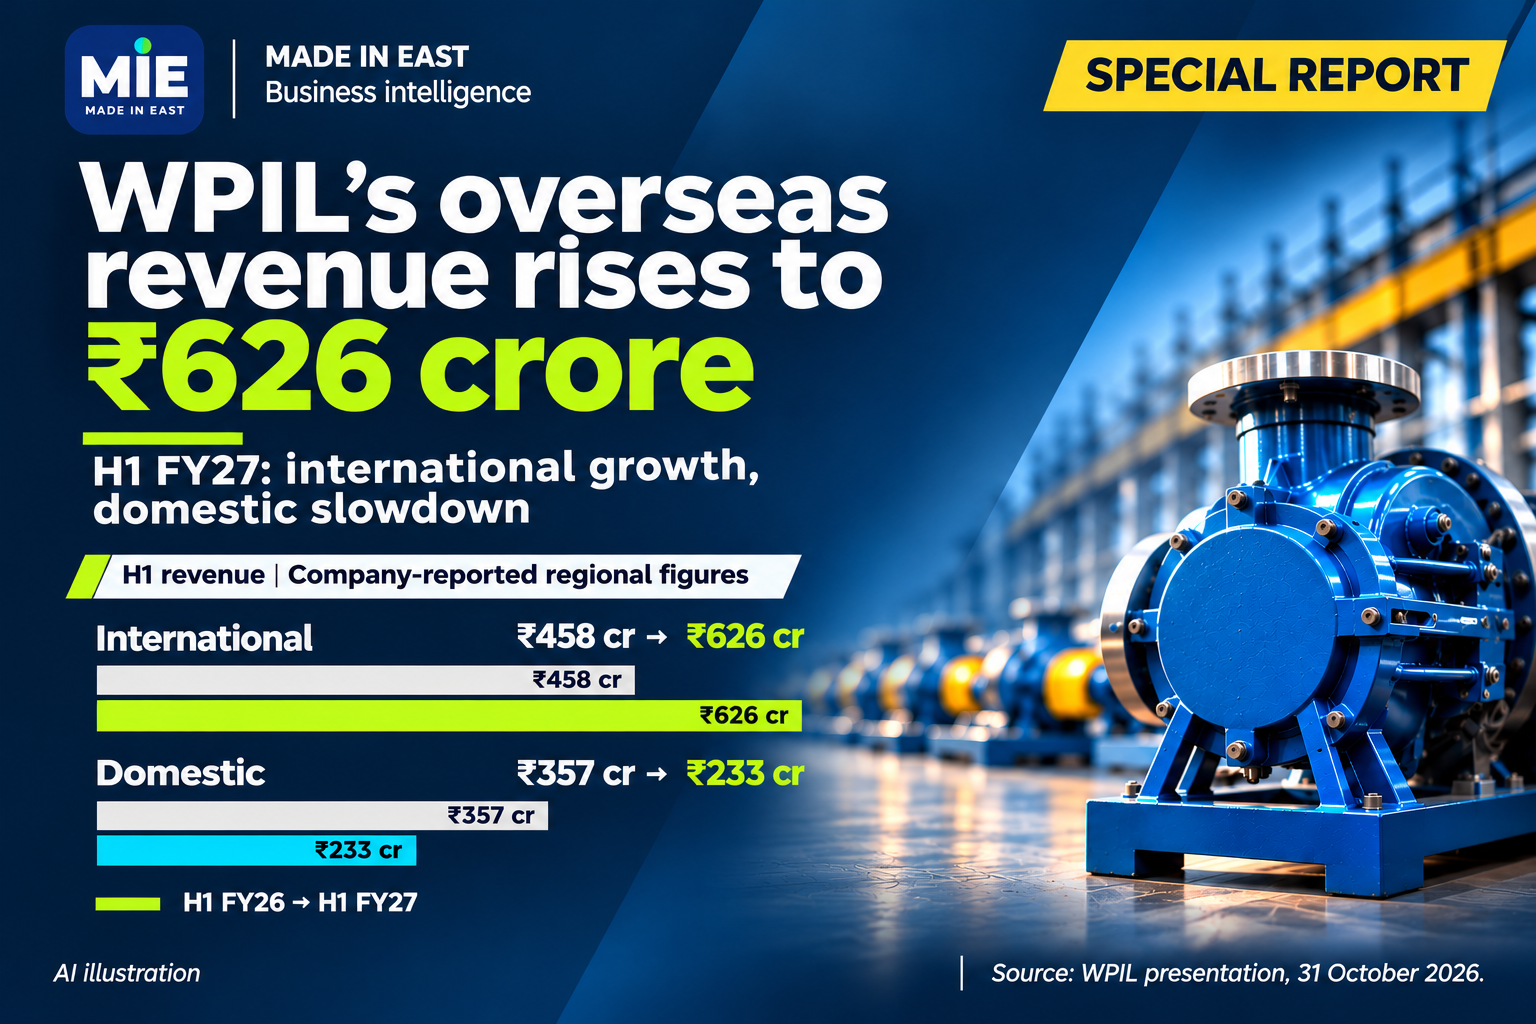
In its regional commentary, WPIL puts first-half domestic revenue at approximately ₹233 crore, against ₹357 crore, and international revenue at ₹626 crore, against ₹458 crore. The comparison describes business already reported for April to September, rather than a new November order.
The domestic product division had a positive outlook and an order book approaching ₹500 crore, but customers deferred a large number of dispatches during the quarter, according to the company. That is a distinction between orders held and products delivered. The filing does not identify the affected customers or quantify the deferred revenue.
Domestic project activity remained subdued. WPIL says it is concentrating on commissioning projects and starting operation and maintenance work. Management expects improvement in the second half, but that remains an expectation. It is not evidence that dispatch delays have cleared or that every project has entered service.
Why the Kolkata connection matters
WPIL’s regional relevance goes beyond its registered office in Salt Lake. Its manufacturing network includes two Kolkata engineered-pump locations. The group’s operating businesses also span Italy, South Africa and Australia, serving pumps, flow-control and water-infrastructure markets.
Its earlier presentation, dated 7 November 2025, describes the expansion through acquisitions including Sterling Pumps and South African pump businesses, followed by Gruppo Aturia in Italy and later project capabilities. The current results test how that international operating network performs alongside the Indian business. They do not establish that all overseas revenue represents exports from West Bengal.
The overseas pipeline and its limits
WPIL reports an international order book of around ₹2,700 crore. It says MISA Italy completed its legacy projects and booked orders during the quarter, PCI Africa’s new projects had started, and Eigenbau secured a repeat Riverton Water Works order. These are different stages of work. The presentation does not provide individual award dates and values sufficient to turn them into separate fresh contract reports.
An anticipated Kuwait Water Supply order remains prospective. PCI Africa’s further execution pickup in 2027 is also forward-looking. Neither belongs in a tally of completed revenue or newly confirmed awards.
What industry readers should watch
For manufacturers, the immediate test is whether deferred dispatches turn into deliveries without a further margin setback. For water-project businesses, commissioning and the start of maintenance work can change the revenue mix, but the filing does not establish a maintenance-margin advantage.
For readers assessing the group, revenue, EBITDA and cash collection answer different questions. The present analysis does not establish that reported profit has converted into operating cash. A subsequent review of the original cash-flow and working-capital disclosures is needed before making that claim.
The next checkpoints are dated commissioning updates, domestic dispatch progress, maintenance revenue and the pace of overseas project delivery. A stronger next period would provide more useful evidence than the order book alone.
A note on the figures
The current presentation describes international growth as 38%, while its rounded ₹626 crore and ₹458 crore figures imply about 36.7%. Its regional commentary also does not provide an exact bridge to consolidated revenue. MIE therefore retains the attributed regional amounts, uses the consolidated financial tables for group totals and avoids putting the disputed percentage in the headline or visual.
Sources
WPIL, 31 October 2026 earnings presentation, PDF pages 9–10, 19–23 and 26–27. WPIL, 7 November 2025 presentation, corporate history and international operations. Figures are company disclosures, not independently audited findings by MIE.
Cover: publisher-supplied AI illustration of industrial pumps, not a photograph of a WPIL facility or product. Numerical labels show the company-reported rounded regional figures.